2026-08-08 · 8 min read · Santa Clarita · last reviewed 2026-08-13
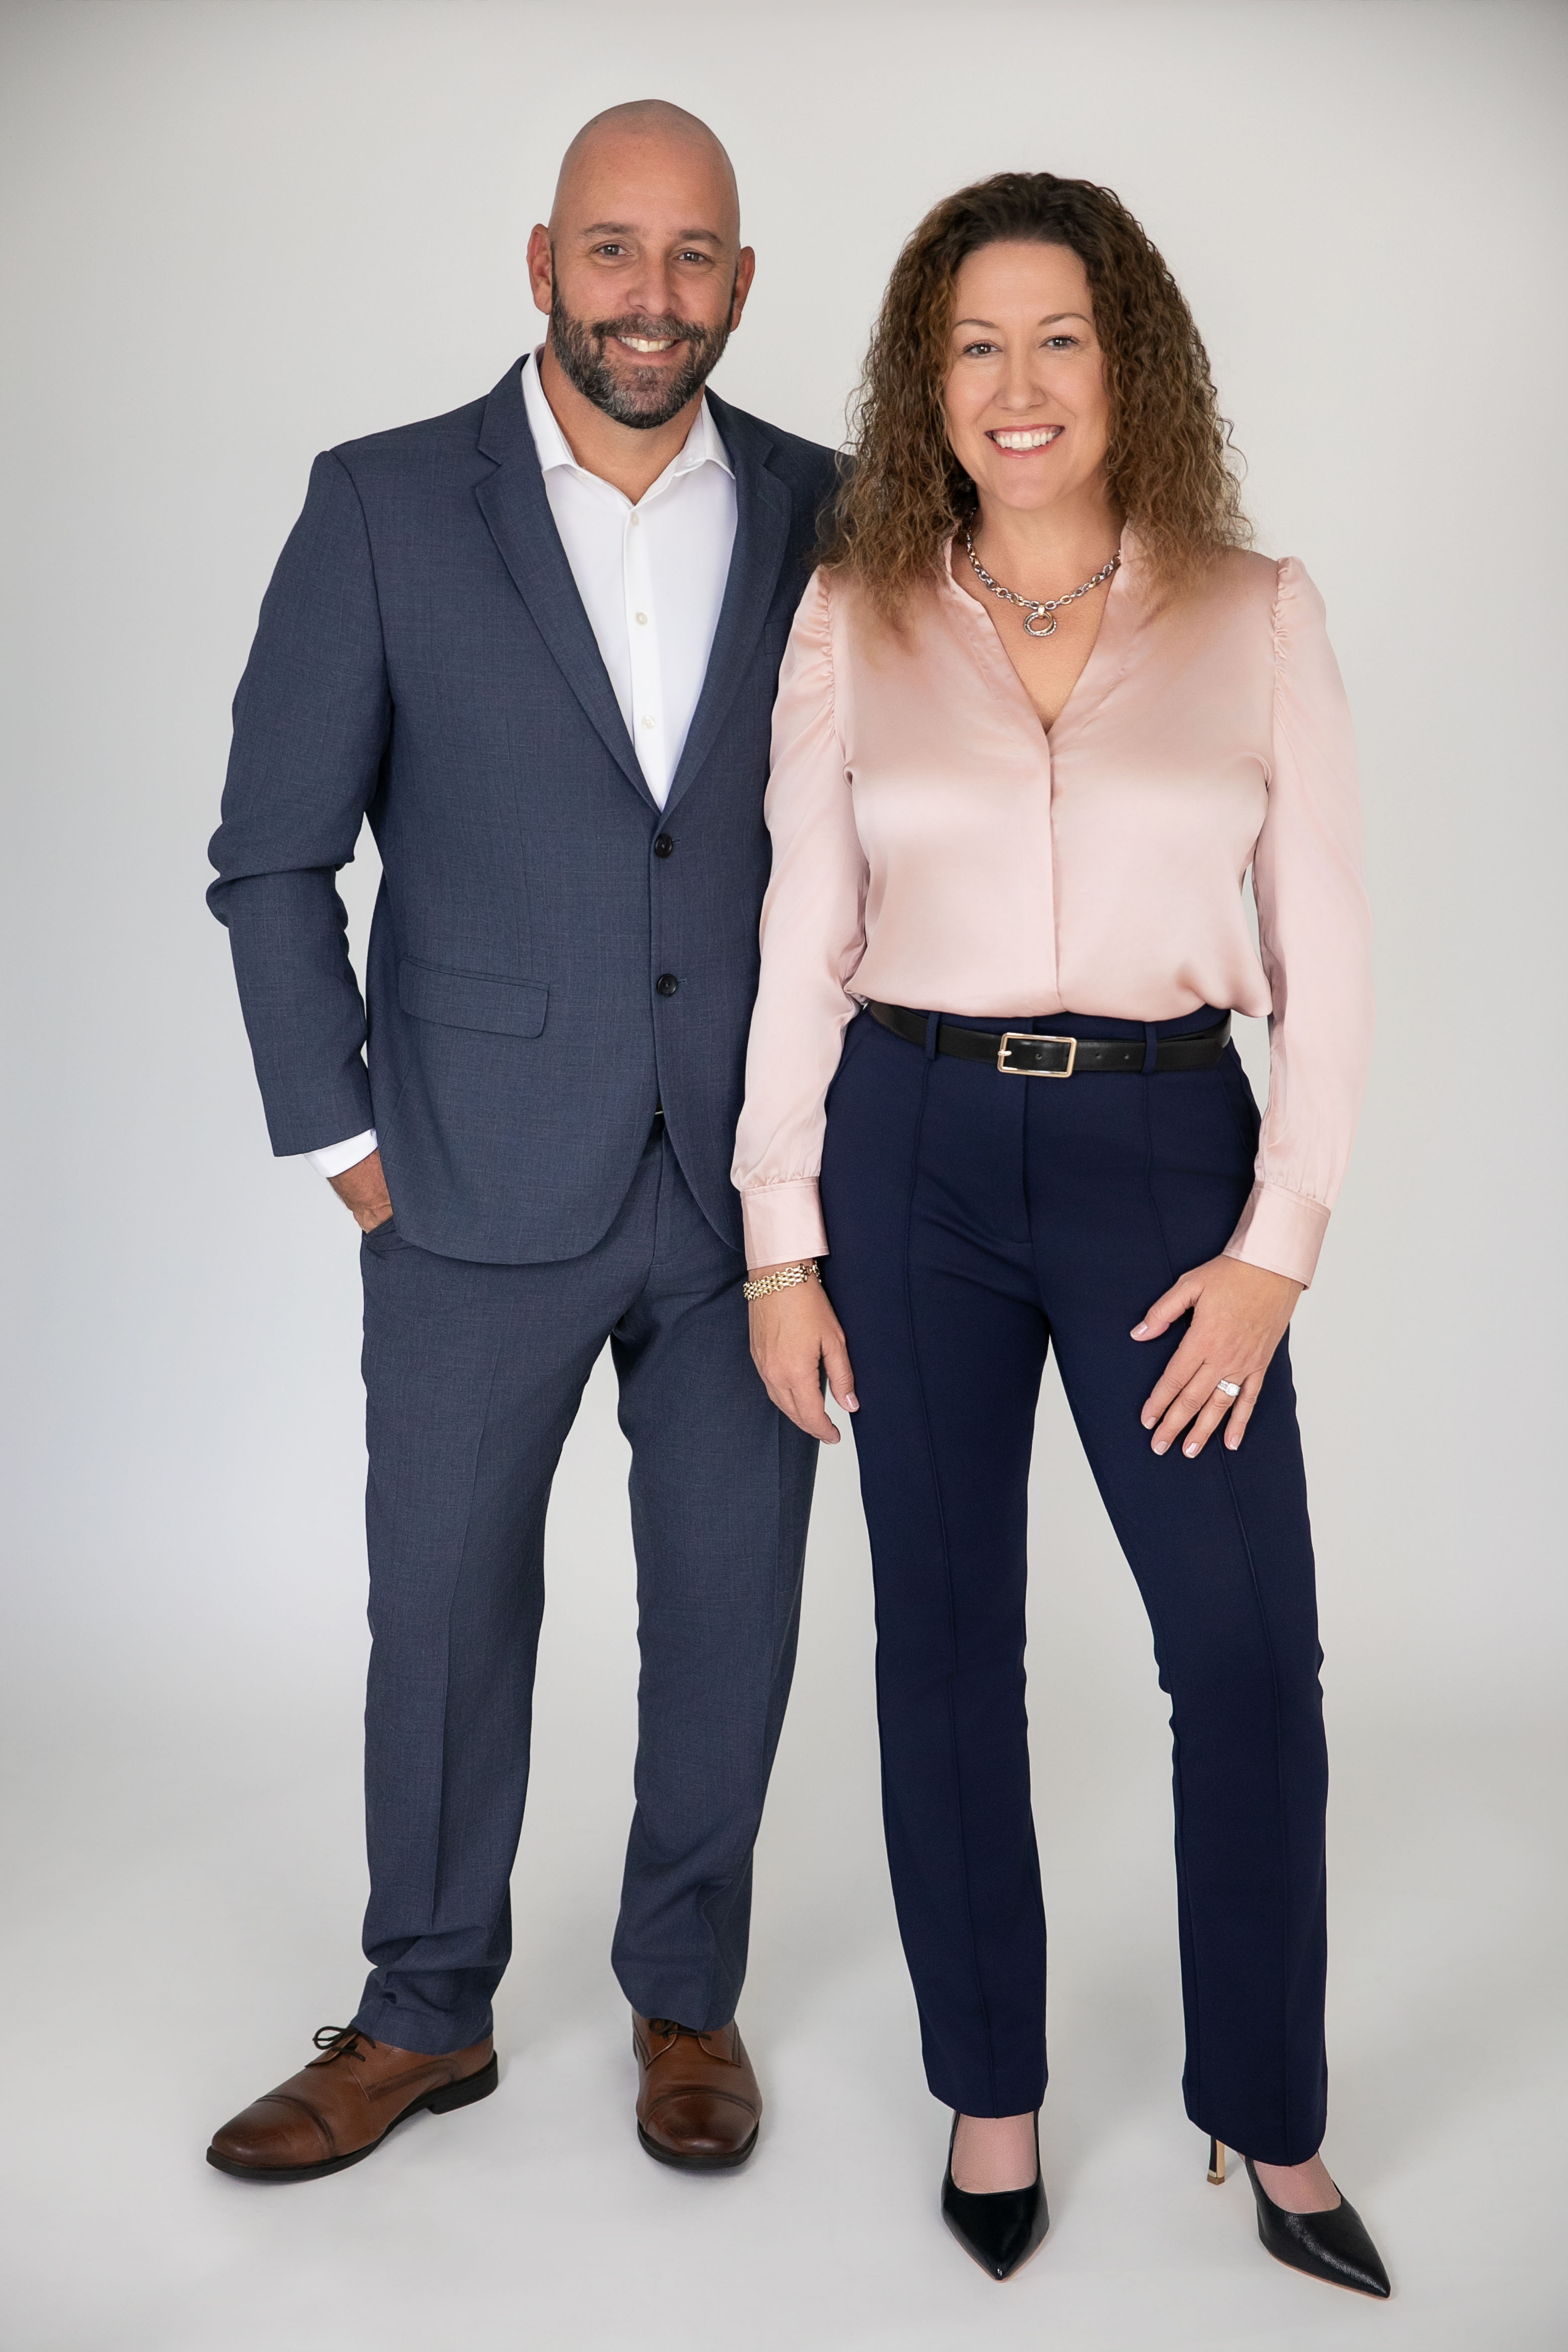
By Michelle Dubner, REALTOR® · DRE #01496647 · Dubner Real Estate Group
Mortgage Rates This August: Santa Clarita Buyers
What is the current 30-year mortgage rate for Santa Clarita buyers?
Santa Clarita's Jon and I explain what this August's mortgage rate move actually means for your home search and your budget.
Part of Buying a home
Overview
Published by Michelle & Jon Dubner | Dubner Real Estate Group | Equity Union
If you're watching mortgage rates before you start touring homes in Santa Clarita, here's the plain answer: the average 30-year fixed rate ticked up slightly this week, landing at 6.69% according to Freddie Mac's weekly survey, up from 6.66% the week before. That's a small move, not a reason to pause your search. Jon and I hear about this number from buyers constantly, and the honest read this week is that rates are bouncing around inside a narrow range, sometimes dropping within the same week they rose. Here's what this specific move actually means for your budget and your next step.
Key Takeaways- Freddie Mac's weekly benchmark put the 30-year fixed at 6.69% for the week of August 6, 2026, up slightly from 6.66% the week before.
- Other sources showed real spread in that same window: Bankrate was around 6.76%, and NerdWallet showed a same-day dip to 6.54% APR on August 8. Your actual rate depends on your lender, not the headline average.
- A move this small isn't a signal to wait. Rates shift in both directions inside the same week, sometimes the same day.
- Get pre-approved and collect real quotes from two or three lenders before deciding whether to lock your rate or let it float.
More on that in what working with us looks like for buyers.
What did mortgage rates actually do this week?
According to Freddie Mac's Primary Mortgage Market Survey, the standard weekly benchmark most agents and lenders quote, the average 30-year fixed rate came in at 6.69% for the week of August 6, 2026. That's up from 6.66% the week before, a move of three-hundredths of a point. In plain terms, that's not a shift that should change your plans if you're actively looking at homes in Santa Clarita or anywhere in the surrounding Los Angeles area. It's the kind of week-to-week noise that happens constantly, and it's worth watching over months, not days.
Why do different sources show different rates on the same day?
This is the part that trips buyers up. In that same window, Bankrate showed an average closer to 6.76%, while NerdWallet showed a same-day dip to 6.54% APR on Saturday, August 8. Three real sources, three different numbers, all accurate for what they're measuring. Freddie Mac surveys lenders about primary, conforming loans with strong credit and a standard down payment. Bankrate and NerdWallet pull from a mix of live lender quotes that shift by the hour based on your credit score, your loan amount, your down payment, and which lender you ask. The takeaway isn't "which number is right." It's that a headline rate is a starting point, not your actual rate. The only way to know your real number is to get quotes from real lenders.
Should I wait for rates to drop before I start looking in Santa Clarita or LA?
We get this question every week, whether someone is searching in Santa Clarita specifically or comparing homes across the broader Los Angeles market. Here's the honest answer: nobody, including us, can tell you where rates go next. What we can tell you is what actually happened this week: rates went up slightly on the primary benchmark, and dropped on a same-day lender quote. That's not a trend you can time. Waiting for a "better" rate often means competing with more buyers once rates do move, since demand tends to pick up the moment rates ease. If a home works for your budget today, the math should drive the decision, not a guess about next month's headline.
What's the difference between locking and floating my rate?
Once you're in contract, your lender will ask if you want to lock your rate or let it float. Locking means your rate is fixed for a set period, usually 30 to 60 days, while your loan closes. If rates rise after you lock, you're protected. If they drop, you don't get the lower rate unless your lender offers a float-down option, which some do for a fee. Floating means you're betting the other direction: you wait, hoping the rate improves before closing, but you're exposed if it moves up instead. Most buyers in a normal market, especially with rates moving inside a narrow band like they are right now, are better off locking once they have a number they can afford. Ask your lender directly whether a float-down option exists before you decide.
What should I actually do this week if I'm planning to buy?
Three things, in order. First, get pre-approved if you haven't already, so you know your real number instead of guessing off a headline rate. Second, get quotes from at least two or three lenders, since we just showed you a 0.22-point spread between sources on the exact same day. Third, run your own monthly payment math at a couple of different rate scenarios so you know your comfort range before you're standing in a home you love. None of that requires guessing where rates go next. It just requires knowing your own numbers cold.
📍 See Dubner Real Estate Group on Google: homes for sale in Santa Clarita
If you want to talk through what this week's rates actually mean for your specific budget, call or text us at 661-219-5517. We'll walk through the real numbers with you, not just the headline.
Michelle & Jon Dubner · Dubner Real Estate Group · Equity Union
If you want the practical version of this for your own situation, here is our buyer process from first search to keys.