For buyers
Buying a home in Los Angeles County
Whatever kind of buyer you are, this is where to start. Then dig into the neighborhood you actually want to live in.
Start here
Help me find a home
Tell us the beds, baths, and square footage you need, the neighborhoods you have in mind, the things you really want, and anything about your family we should know. We read every one ourselves and come back to you with homes that actually fit, including ones you would scroll past online.
Buyer resources
Buying a Home
Find a home you love without feeling rushed, pushed, or unsure of what happens next.
Learn more →
First-Time Buyers
Your first home should feel exciting, not confusing. We explain every step in plain language.
Learn more →
Relocating to the Area
Moving somewhere new? We help it feel familiar before you ever unpack a box.
Learn more →
VA and Military Buyers
You've served. Buying a home should be the easy part, planned around your timeline and orders.
Learn more →
Trading Up
Outgrown your home? Sell it and buy the next one without juggling two moves on your own.
Learn more →
Buying an Investment Property
Buy a rental property with the numbers in front of you, so it builds your future instead of your stress.
Learn more →By neighborhood
Buying in your exact area
The two things buyers are actually afraid of
Overpaying, and losing the house they loved to somebody else's offer. Almost every question a buyer asks is really one of those two wearing a different coat.
Both are preventable, and both get decided before you ever tour a home. Not during. Before.
The buyer who gets the good house is almost always the one who was already prepared when it came up on a Thursday night. Not the one with the biggest budget.
Tell us what you are looking for
What you can actually afford, which is not what you are approved for
A lender will approve you for a payment. Whether you want to live on that payment is a different question, and it is yours, not theirs.
So before we look at a single house, we look at what the monthly number really includes here:
- Principal and interest, the part everybody thinks about.
- Property taxes. In California your taxes reset to roughly 1.1 to 1.3 percent of what you pay, not what the seller was paying. People are routinely shocked by this.
- Insurance, which in parts of this county is affected by fire hazard designation and is worth quoting before you are in escrow, not during.
- Mello-Roos and special assessments. Many newer Santa Clarita Valley neighborhoods sit in a Community Facilities District, and that bond shows up on the tax bill every year. It can be a few hundred dollars or a few thousand.
- HOA dues, if there is one.
Two homes at the same price can carry very different monthly costs once those are in. We will show you the real number on anything you are serious about, before you fall for it.
What you need up front
The down payment is not the only cash you need. Closing costs, the appraisal, inspections, and your earnest money deposit all land in the same stretch of weeks.
You do not necessarily need 20 percent. Conventional loans go lower, FHA lower still, and a VA loan can mean nothing down for a qualifying veteran. Less down usually means mortgage insurance, which is a real cost and worth seeing in the monthly number rather than discovering later.
Your deposit is usually one to three percent, and it goes to escrow, not to the seller. It is credited to you at closing. It is genuinely at risk only after you remove your contingencies, which is why those dates matter so much.
What you pay us gets agreed in writing first. California now requires a written agreement between a buyer and their agent before showings, which is a good change, because it puts the money conversation at the beginning instead of the middle. In many transactions the seller still offers compensation to the buyer's agent, and we will tell you exactly how it works on any home you are considering.
How the search actually works
Most buyers start by scrolling. That is fine, it is how everybody starts, but it tends to produce a list of houses that look good in photographs rather than houses that fit the life you are living.
So we build the search around your week, not your bedroom count. The commute you will actually make every day. Whether you need a yard or genuinely do not. Whether stairs matter now or might in ten years. Where you will be on a Saturday.
Then, on each home we see, we tell you what we see. The good and the not so good. We would much rather talk you out of a house in the driveway than watch you find the problem during inspections.
You will tour fewer homes that way, and the ones you do see will be worth your Saturday. Tell us what you are looking for and we will start the search.
Writing an offer that actually holds together
Price is one term. It is not the only one, and in a competitive situation it is often not the one that wins.
What a seller is really asking is whether your offer will close. So we make sure yours answers that: a lender who has actually underwritten you rather than glanced at a form, a deposit that signals you are serious, contingency periods that are realistic rather than theatrical, and a closing date that works for where the seller is going.
On the California standard form, the buyer contingencies default to 17 days for investigation, appraisal, loan, and homeowner's insurance. Every one is negotiable. Shortening them makes an offer look stronger, and it only makes sense if you can genuinely perform in that window. A ten-day loan contingency from a lender who has not started underwriting is a promise nobody can keep, and experienced listing agents know it.
Writing an offer that actually holds together
A yard that earns its keep
Whatever kind of buyer you are
Different situations genuinely need different handling, not just a different brochure:
- Buying your first home, explained in plain language with nothing assumed.
- Moving up, where you have to sell and buy on one timeline.
- Relocating here from elsewhere in California or out of state.
- Buying with a VA loan, including how to write an offer a seller will take seriously.
- Buying an investment property, with the rent math done honestly.
- Buying new construction, where the builder's representative works for the builder and you should have someone of your own.
Frequently Asked Questions
How much home can I actually afford?
How much do I need for a down payment?
Do I have to be pre-approved before we start looking?
What does it cost me to work with a buyer's agent?
How long does it take to buy a home?
What are contingencies and how long do I get?
Should I buy now or wait?
Do I need to sell my current home first?
What is Mello-Roos and will I have to pay it?
Do you only help buyers in Santa Clarita?
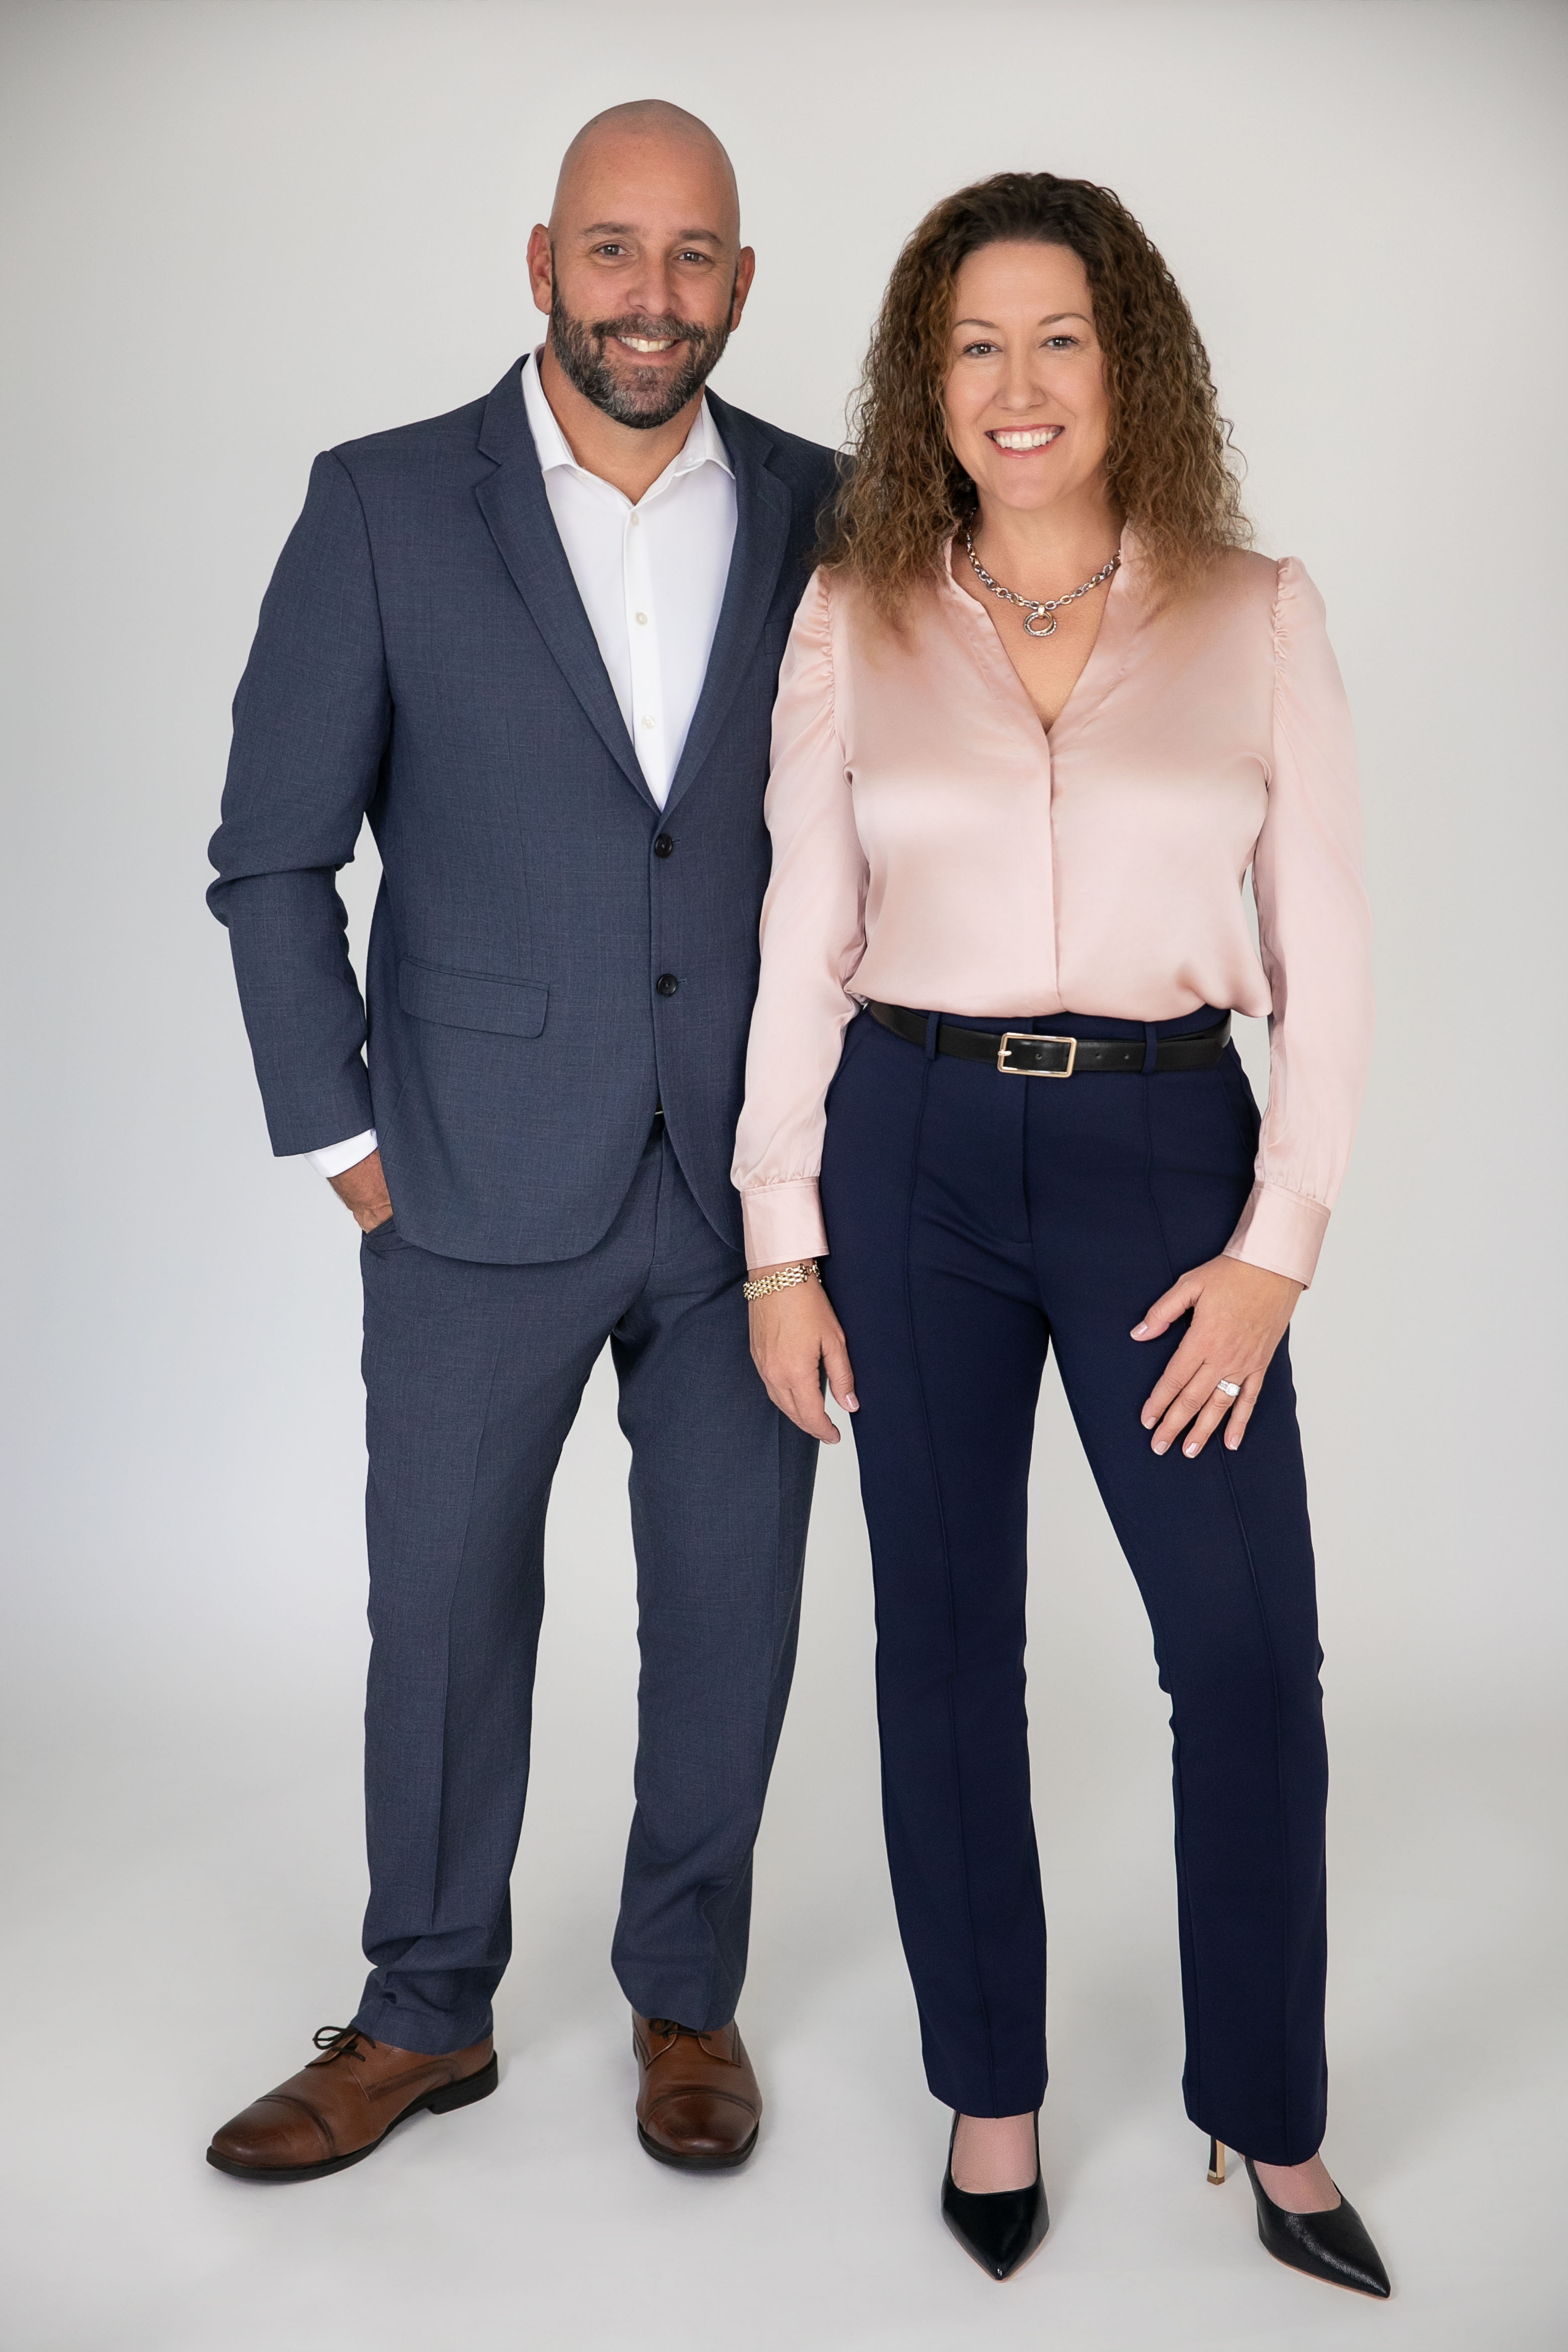
Meet the team
The team that would help you buy
We are Michelle and Jon Dubner, husband and wife, and Dubner Real Estate Group is ours. Our team is here to serve you: to understand what you are hoping for, walk you through it step by step, and make sure you get there. Michelle answers her own phone and is quickest by text, so ask us anything, at any point, however small it feels.
Michelle Dubner DRE #01496647 Jon Dubner DRE #02118617 Equity Union
Reading for buyers
All 64 articles →
2026-09-13 · 8 min
Santa Clarita Homeowners Insurance Checks
2026-09-13 · 8 min
Official Santa Clarita Resources Every Home Buyer Should Read
2026-09-13 · 8 min
Santa Clarita Neighborhood Checks
2026-09-12 · 9 min
Where to Look Up Santa Clarita Zoning and Planning Records
2026-09-12 · 8 min
SCV Area Plan: What Owners Can Verify
2026-09-11 · 9 min
What the SCV Area Plan Helps Verify
Keep exploring
Ready to make your move with Dubner Real Estate Group?