Buying a home
Buying a Home in Los Angeles County
The buyer who gets the good house is the one who was ready before it came up. Here is how we get you there, from first conversation to keys.
Excited One Minute, Nervous the Next
If you've been scrolling listings late at night, saving homes you love and then talking yourself out of every one, you're in good company. Buying a home is one of the biggest decisions you'll ever make, and it usually lands on top of a full life: work, kids, a lease ending, a commute you're tired of.
Most buyers tell us the same two worries in the first conversation. They don't want to overpay, and they don't want to be pushed into something they'll regret. Both are fair. We'd feel the same way.
Here's how we think about our job. You should walk into every showing knowing what you can afford, what the home is likely worth, and what questions to ask. You should never sign anything you don't understand. And you should feel like you have a team in your corner who care more about you getting the right home than about getting a deal closed this month.
Let's talk about your next move
Most Agents Show You Houses. We Get You Ready to Win One.
The buyers who lose the home they wanted are almost never the ones who searched too slowly. They are the ones who were not ready to write a strong offer the week the right house appeared. By the time you spot a house on a Thursday night, the person who is going to end up owning it has usually already done the work you are about to start.
So our whole process runs backward from that Thursday. Four steps, and they go in this order for a reason.
Ready. Fully pre-approved before you tour anything, working from a real monthly number you have looked at and agreed to, not the maximum a lender was willing to say out loud.
Educated. You know what your budget actually buys in the neighborhoods you like, and you know what to look at in a house besides the paint. Nothing about the process arrives as a surprise the week it happens to you.
Aligned. The search is built around your commute, your schedule and your Saturday instead of a bedroom count, so the homes you give up a weekend for are worth the drive.
Locked. We plan the offer together before it gets written, and then every contract deadline gets tracked until the keys are in your hand.
Do those four and the good house on a Thursday night is a decision you get to make calmly. Skip them and you spend that week catching up while somebody else writes.
Most Agents Show You Houses. We Get You Ready to Win One.
The room that makes people stop
Two Different Numbers, and the Second One Matters More
Your lender will tell you what you can borrow. That is not the same as what you want to spend every month, and the second number is the one that decides how the next few years feel.
Before you tour anything, get fully pre-approved, not pre-qualified. A pre-approval means a lender has actually looked at your documents. In a competitive situation a seller can tell the difference immediately.
Then build the real monthly number: principal and interest, property taxes, insurance, HOA dues if any, and Mello-Roos if the tract has it. That last one catches people here. By law it is never calculated on your assessed value. It runs off a formula tied to square footage, lot size, or land use, so two neighbors on the same street can pay very different amounts. In established Santa Clarita tracts it commonly lands somewhere around $1,000 to $3,500 a year, and the newest master-planned communities run higher. The only number that counts is the one on that parcel's actual tax bill, and we pull it before you write.
A lower-priced home with dues and a special assessment can cost more per month than a higher-priced one with neither. We run both numbers on every home you are serious about.
What It Costs You to Work With Us
For most of our buyers, nothing out of pocket. Here is how it actually works in 2026, because the rules changed.
You and we sign a written buyer representation agreement up front that states plainly what we are owed, before we start touring. That is required now, and it is a good thing: you know the number instead of guessing.
Then, on any specific home, the seller most often still covers it, either through compensation offered by the listing side or as a seller concession credited at closing. What changed is that it is negotiated per property rather than advertised in the MLS.
If a particular listing offers less than our agreement, you have real options: ask for a concession to bridge the gap, adjust the offer price, or move on. We decide that before writing an offer, never after. And we tell you the number on a given house before you get attached to it.
What It Costs You to Work With Us
The pantry that does the quiet work
Choosing Where You'll Wake Up Every Morning
We live and work in the Santa Clarita Valley, and we help buyers all over Los Angeles County. The right area comes down to how you want your days to feel. How long is the drive at the hour you'd leave for work? Do you want a newer planned community with parks and trails, or an older street with a bigger lot and no HOA? Is a pool, an RV pad, or room for a home office on your must-have list?
Across the valley, Valencia, Saugus, Newhall, Canyon Country, Stevenson Ranch, and Castaic each have their own housing styles, price ranges, and pace. If your search reaches into the San Fernando Valley, Burbank, Glendale, or the Antelope Valley, we cover that ground too. See the greater Los Angeles areas we serve.
One tip we give everyone: drive the commute at rush hour before you write an offer. A map says 25 minutes. Monday at 7:15 might say something else.
From Your First Showing to the Day You Get the Keys
Every purchase has its own twists, and none of them go exactly to plan. What makes the difference is knowing the shape of the thing before you are standing inside it, because nearly all the panic in a home purchase comes from a step showing up that nobody warned you was coming.
So here is the whole path, in the order it actually happens.
- We sit down together. We talk through your budget, timeline, and what matters most. Before we tour, we sign a written buyer agreement that spells out what we do for you and how we're paid. We explain every line, and the terms are negotiable.
- We build your search. Tell us what you want with a custom home search request and we'll send homes that fit, including ones worth a second look that you'd scroll past online.
- We tour and compare. We point out what photos hide: roof age, drainage, the busy street behind the back fence.
- We write a strong offer. We study recent sales so your price is grounded in real numbers, then shape terms a seller will take seriously.
- We protect you in escrow. Your contract sets deadlines for inspections, the appraisal, and your loan. We track every one and help you decide what to ask for if the inspection turns something up.
- We walk it one last time. The final walkthrough confirms the home is in the condition you agreed to. Then you sign and it's yours.
Want more detail on each stage? Our buying process page goes deeper.
What Contingencies Actually Protect
Contingencies are the conditions that let you walk away and keep your deposit. Understanding them is the difference between a confident offer and a reckless one.
- Inspection. You verify the house and can renegotiate or exit based on what you find.
- Appraisal. Protects you if the home does not appraise for the price.
- Loan. Protects you until financing is actually approved, not just pre-approved.
- Sale. Only if your purchase depends on your current home selling. This is the one sellers discount heavily.
Waiving a contingency makes an offer stronger and moves risk onto you. Sometimes that is the right call. It should always be a decision you made deliberately with the numbers in front of you, not something an agent talked you into in a bidding war.
What Contingencies Actually Protect
The bath you were promised
The Inspections Worth Paying For
Get the general inspection, then pay for the two or three specialist follow-ups it recommends. Usually that is a sewer scope, a roof inspection, and HVAC.
A few hundred dollars there turns a vague worry into a real number you can negotiate with or walk away from. On older homes in this valley the issues cluster predictably: roof age, original galvanized plumbing, an undersized or problem-brand electrical panel, a furnace or AC near end of life, sewer line condition, and original windows.
Insurance is now its own inspection. Get a quote during your contingency period, not after. If a home sits in a high fire hazard severity zone, admitted carriers may decline it and you end up on the California FAIR Plan, which as of September 2026 averages roughly $3,000 to $3,200 a year statewide against about $1,480 for a standard admitted policy, with high-risk zones running well past that. A large rate increase filed in October 2025 is working its way through the Department of Insurance, so treat those averages as a starting point and get a real quote on the actual address. The FAIR Plan covers fire, lightning, internal explosion and smoke, but not liability, water damage, theft or loss of use, so most people add a separate difference in conditions policy on top to get back to normal coverage. A payment you can afford and that payment plus $600 a month of insurance are two different houses.
How Long This Takes
Two different clocks, and people usually mean the first one.
The search is unpredictable. Some buyers find it the first weekend, others look for months, and it comes down to how specific your criteria are and what is actually on market that fits.
Escrow is the predictable part: roughly 30 to 45 days on a financed purchase, faster when the lender is sharp and you are fully documented, a week or two on cash.
What shortens the whole thing is being ready before you tour: fully approved, clear on your must-haves, and decided in advance about how you will handle a competitive situation.
What Working With Us Looks Like
You work with our team and we guide you on every step. On a purchase you may also work with Stephanie Tiffany, our REALTOR® and Buyer Specialist. You meet everyone before anything starts.
We show you what to look at beyond the paint: the age of the roof, signs of water damage, how the lot drains, what the neighbors did to their houses. We will tell you when a house is not the one, even when it would be easier to let you fall for it.
Tell us what you are looking for through our custom home search, or start with our full buying process. Then explore the neighborhoods.
Ready When You Are
You don't have to know which neighborhood, which loan, or which house yet. Start with a conversation. Book an appointment or call us at 661-219-5517 and we'll map out what your first few steps look like.
Buying your very first home? Our first-time buyer page starts from zero. Need to sell before you buy? Start with selling and buying at the same time and find out what your current home is worth.
Frequently Asked Questions
Where do I start if I want to buy a home?
How much home can I afford?
How much do I need for a down payment?
What are closing costs, and how much should I plan for?
What is Mello-Roos, and will the home I like have it?
Should I get pre-qualified or pre-approved?
Do I have to sign an agreement before we tour homes?
Is now a good time to buy, or should I wait?
What happens if my offer isn't accepted?
What if the appraisal comes in lower than the price?
Do you only help buyers in Santa Clarita?
Keep exploring
Ready to make your move with Dubner Real Estate Group?
Meet the team
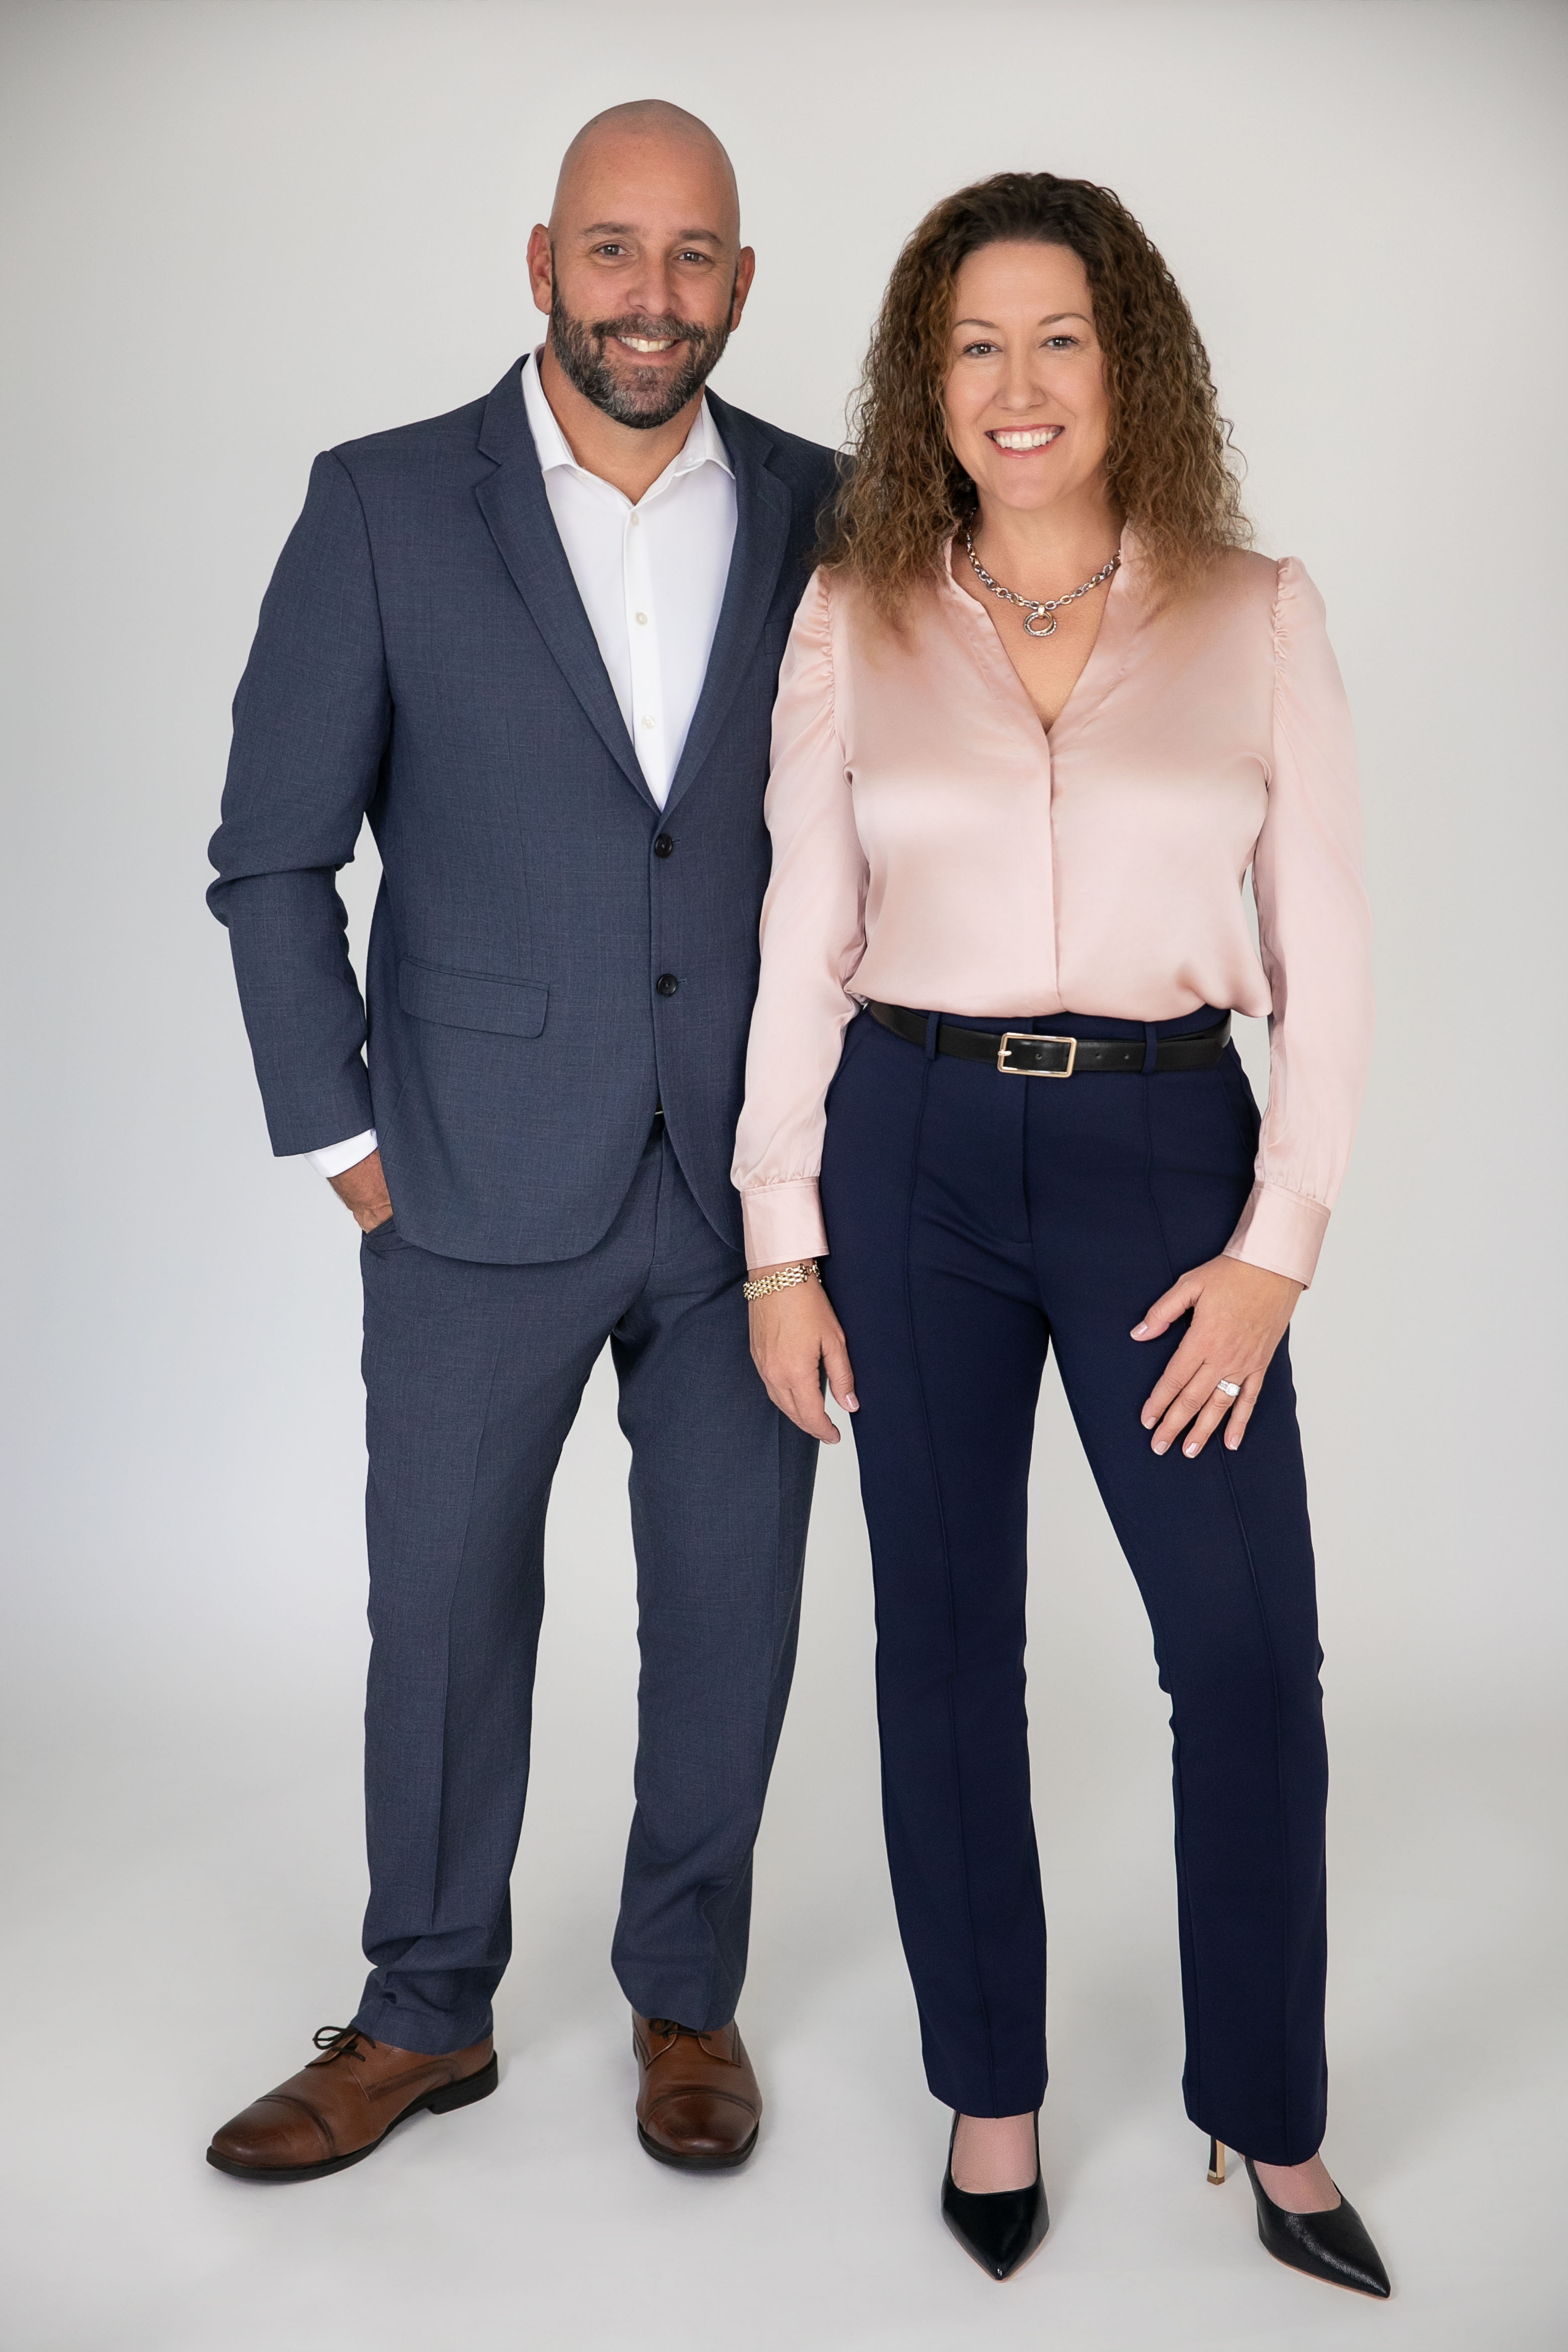
You would be working with our team
We are Michelle and Jon Dubner, husband and wife, and Dubner Real Estate Group is ours. Our team is here to serve you: to understand what you are hoping for, walk you through it step by step, and make sure you get there. Michelle answers her own phone and is quickest by text, so ask us anything, at any point, however small it feels.
Michelle Dubner DRE #01496647 Jon Dubner DRE #02118617 Equity Union