Your free guide
The First-Time Buyer's Guide to Los Angeles County
This one is a workbook. The lender document list, the real budget math, what to check at every showing, and the deadlines that decide whether your deposit is safe.
How to use this
You can read a hundred articles about buying a first home and still not know what to actually do on Monday. So this is the working version: the lists, the numbers, and the deadlines.
If you want the full explanation of how each step works, that is on our buying process page. This page is the homework.
Let's talk about your next move
What your lender will ask for
Nobody enjoys this part. Here is why it is worth doing before you call anyone: a lender with everything in hand can turn a pre-approval around in days, and a lender chasing you for a missing bank statement takes weeks. Those weeks are usually the ones in which the house you would have loved comes up and goes to somebody who was ready. So do the boring afternoon first.
- Two years of W-2s, and two years of tax returns if you are self-employed, on commission, or have rental income.
- Your last 30 days of pay stubs.
- Two months of statements for every account you will use for the down payment. Every page, including the blank ones, because underwriters reject partial statements.
- Photo ID and Social Security number.
- Retirement and investment statements if you are drawing on them.
- Documentation for any large or unusual deposit in the last 60 days. Underwriters will ask about every one of them, and a cash deposit you cannot source usually cannot be counted.
- If any of the money is a gift, a gift letter and proof of where it came from.
- Landlord contact information and 12 months of rent history.
- If you are divorced, the decree, plus documentation of support paid or received.
- Your DD-214 and Certificate of Eligibility if you are using a VA loan.
And then, until you have keys, do none of these: open a new credit card, finance a car, change jobs, move money between accounts without telling your lender, or make a large purchase. Any one of them can undo an approval a week before closing. This is not theoretical; it happens constantly.
What the money actually looks like
Four separate pots. Most first-time buyers only plan for one of them.
1. Down payment. Not necessarily 20 percent. Conventional loans start around 3 percent for qualified first-time buyers, FHA is 3.5 percent, and VA can be zero down. Under 20 percent means mortgage insurance, which is a real monthly cost, and on a conventional loan it comes off eventually. Waiting years to reach 20 percent while prices move is not automatically the better plan; run both versions.
2. Closing costs. Generally 2 to 5 percent of the price: lender fees, appraisal, lender's title insurance, escrow, recording, and prepaid taxes and insurance. On many deals the seller contributes toward these as a concession, negotiated per transaction.
3. Inspections. A few hundred dollars for a general inspection, more with a sewer camera or a roof, pool, or foundation specialist. Paid out of pocket during escrow, and you pay them whether or not the deal closes.
4. Your earnest money deposit, commonly 1 to 3 percent, wired within about three business days of acceptance. This one is not additional, because it gets credited to you at closing. But it is genuinely at risk once you remove your contingencies.
Then the monthly number, which is the one that decides whether you like your life. Principal and interest, plus property taxes at roughly 1.1 to 1.3 percent of purchase price a year in Los Angeles County, plus any Mello-Roos special assessment, plus homeowners insurance, plus mortgage insurance if you have it, plus HOA dues. Two homes at the same price in this valley can differ by several hundred dollars a month once Mello-Roos and HOA are counted. Always compare the monthly payment, never the sticker price.
How to compare the six communities
Score each one on the things that will actually shape your week, not the things that sound good in a listing.
- Your real commute, driven at the hour you would actually drive it. Not the map estimate at 2pm on a Sunday.
- The specific school the address is zoned for, confirmed with the district. Boundaries do not follow neighborhood names, and the closest school is often not the assigned one.
- Mello-Roos, yes or no, and the exact annual amount.
- HOA dues and what they cover. A higher HOA that includes the front yard and a pool can be cheaper than a lower one that includes nothing.
- Fire hazard severity zone, because it affects what homeowners insurance costs and, in some cases, who will write it at all.
- Lot size and what backs up to you. A slope, a road, a wash, or a neighbor's second story.
- Heat. Parts of this valley run noticeably hotter than others in August, and it shows up on your electric bill.
Then go read the community pages, which are written by people who live here: Valencia, Saugus, Canyon Country, Newhall, Stevenson Ranch, and Castaic.
How to compare the six communities
The first morning, before the curtains
What to check at every showing
After the fourth house they all blur. Take the same notes on every one.
Things you cannot change, so they matter most: the location, the lot, the floor plan, the noise, the light at the time of day you are home, and how far the house sits from the road.
Things worth actually doing in the house: turn on the shower and check pressure and how long hot water takes. Open and close windows and interior doors. Look at the electrical panel, and note if it is a brand an inspector will flag. Check for water stains on ceilings and under every sink. Look at where the water goes when it rains, especially on a sloped lot. Check cell service in the room you would work from.
Things to ask the agent: how old are the roof, HVAC, and water heater; is the solar owned, financed, or leased; what does the HOA cover and is any special assessment pending; and why is the seller moving.
Go back a second time before you write on it, at a different hour and ideally on a weekday. Traffic, noise, parking, and light are completely different on a Tuesday at 6pm than on a Sunday at 1pm.
The escrow deadlines that protect you
Once your offer is accepted, dates start running from the day of acceptance. These are the ones that matter.
About 3 business days: your earnest money deposit is wired. Call escrow at a number you looked up yourself to confirm wire instructions before sending anything. Wire fraud in real estate is common and the money does not come back.
About 7 days: the seller's disclosures arrive. Transfer Disclosure Statement, Seller Property Questionnaire, Natural Hazard Disclosure, HOA documents, Mello-Roos information. Read them. We will read them with you and tell you which parts actually matter.
17 days: the default on the standard C.A.R. purchase agreement for all four of your contingencies: investigation, appraisal, loan, and homeowner's insurance. All of them are negotiated on the contract, so check what you actually signed.
The one that matters most: in California, nothing removes automatically. Your contingency stays in force until you sign a written Contingency Removal form. Before you sign, you can generally cancel for a covered reason and get your deposit back. After you sign, your deposit is genuinely at risk. Do not sign it until your inspections are done, your appraisal is in, and your loan is actually approved.
Closing: loan documents, your final walk-through, signing, funding, then recording. In California the home is yours when the deed records with the county, which is the morning after your loan funds. You normally sign a couple of days before that, and the loan funds the day after you sign.
The five mistakes that cost first-time buyers the most
Touring before being properly pre-approved. The house you lose is the one you were not ready to write on. And pre-qualified is not pre-approved; sellers know the difference.
Buying at the top of your approval. Being approved for a number is not a recommendation. Lenders do not know about your car payment plans, your childcare costs, or the trip you take every year.
Comparing sticker prices instead of monthly payments. Mello-Roos and HOA dues can put hundreds of dollars a month between two homes listed at the same price.
Skipping the inspection to win. There are ways to make an offer more competitive without giving up your protection, including a shorter inspection period, a pre-offer inspection, or a larger deposit. Waiving protection should be a decision you made deliberately, not something that happened to you.
Touching your credit during escrow. New card, financed car, job change, or a large purchase. Lenders re-check before funding, and approvals get pulled days before closing over exactly this.
Your next step
You do not need to be pre-approved to call us. Plenty of people start a year out.
Tell us what you are picturing and we will build the search and call you to go through the results, or call or text 661-219-5517.
More on buying your first home with us, or read the full buying process.
Frequently Asked Questions
Do I need 20% down to buy my first home in Santa Clarita?
How much money do I need in total to buy a house in California?
What documents do I need for a mortgage pre-approval?
What is Mello-Roos and how do I know if a house has it?
Should I waive my inspection to compete for a house?
Can I get my deposit back if I change my mind?
Keep exploring
Ready to make your move with Dubner Real Estate Group?
Meet the team
Who wrote this
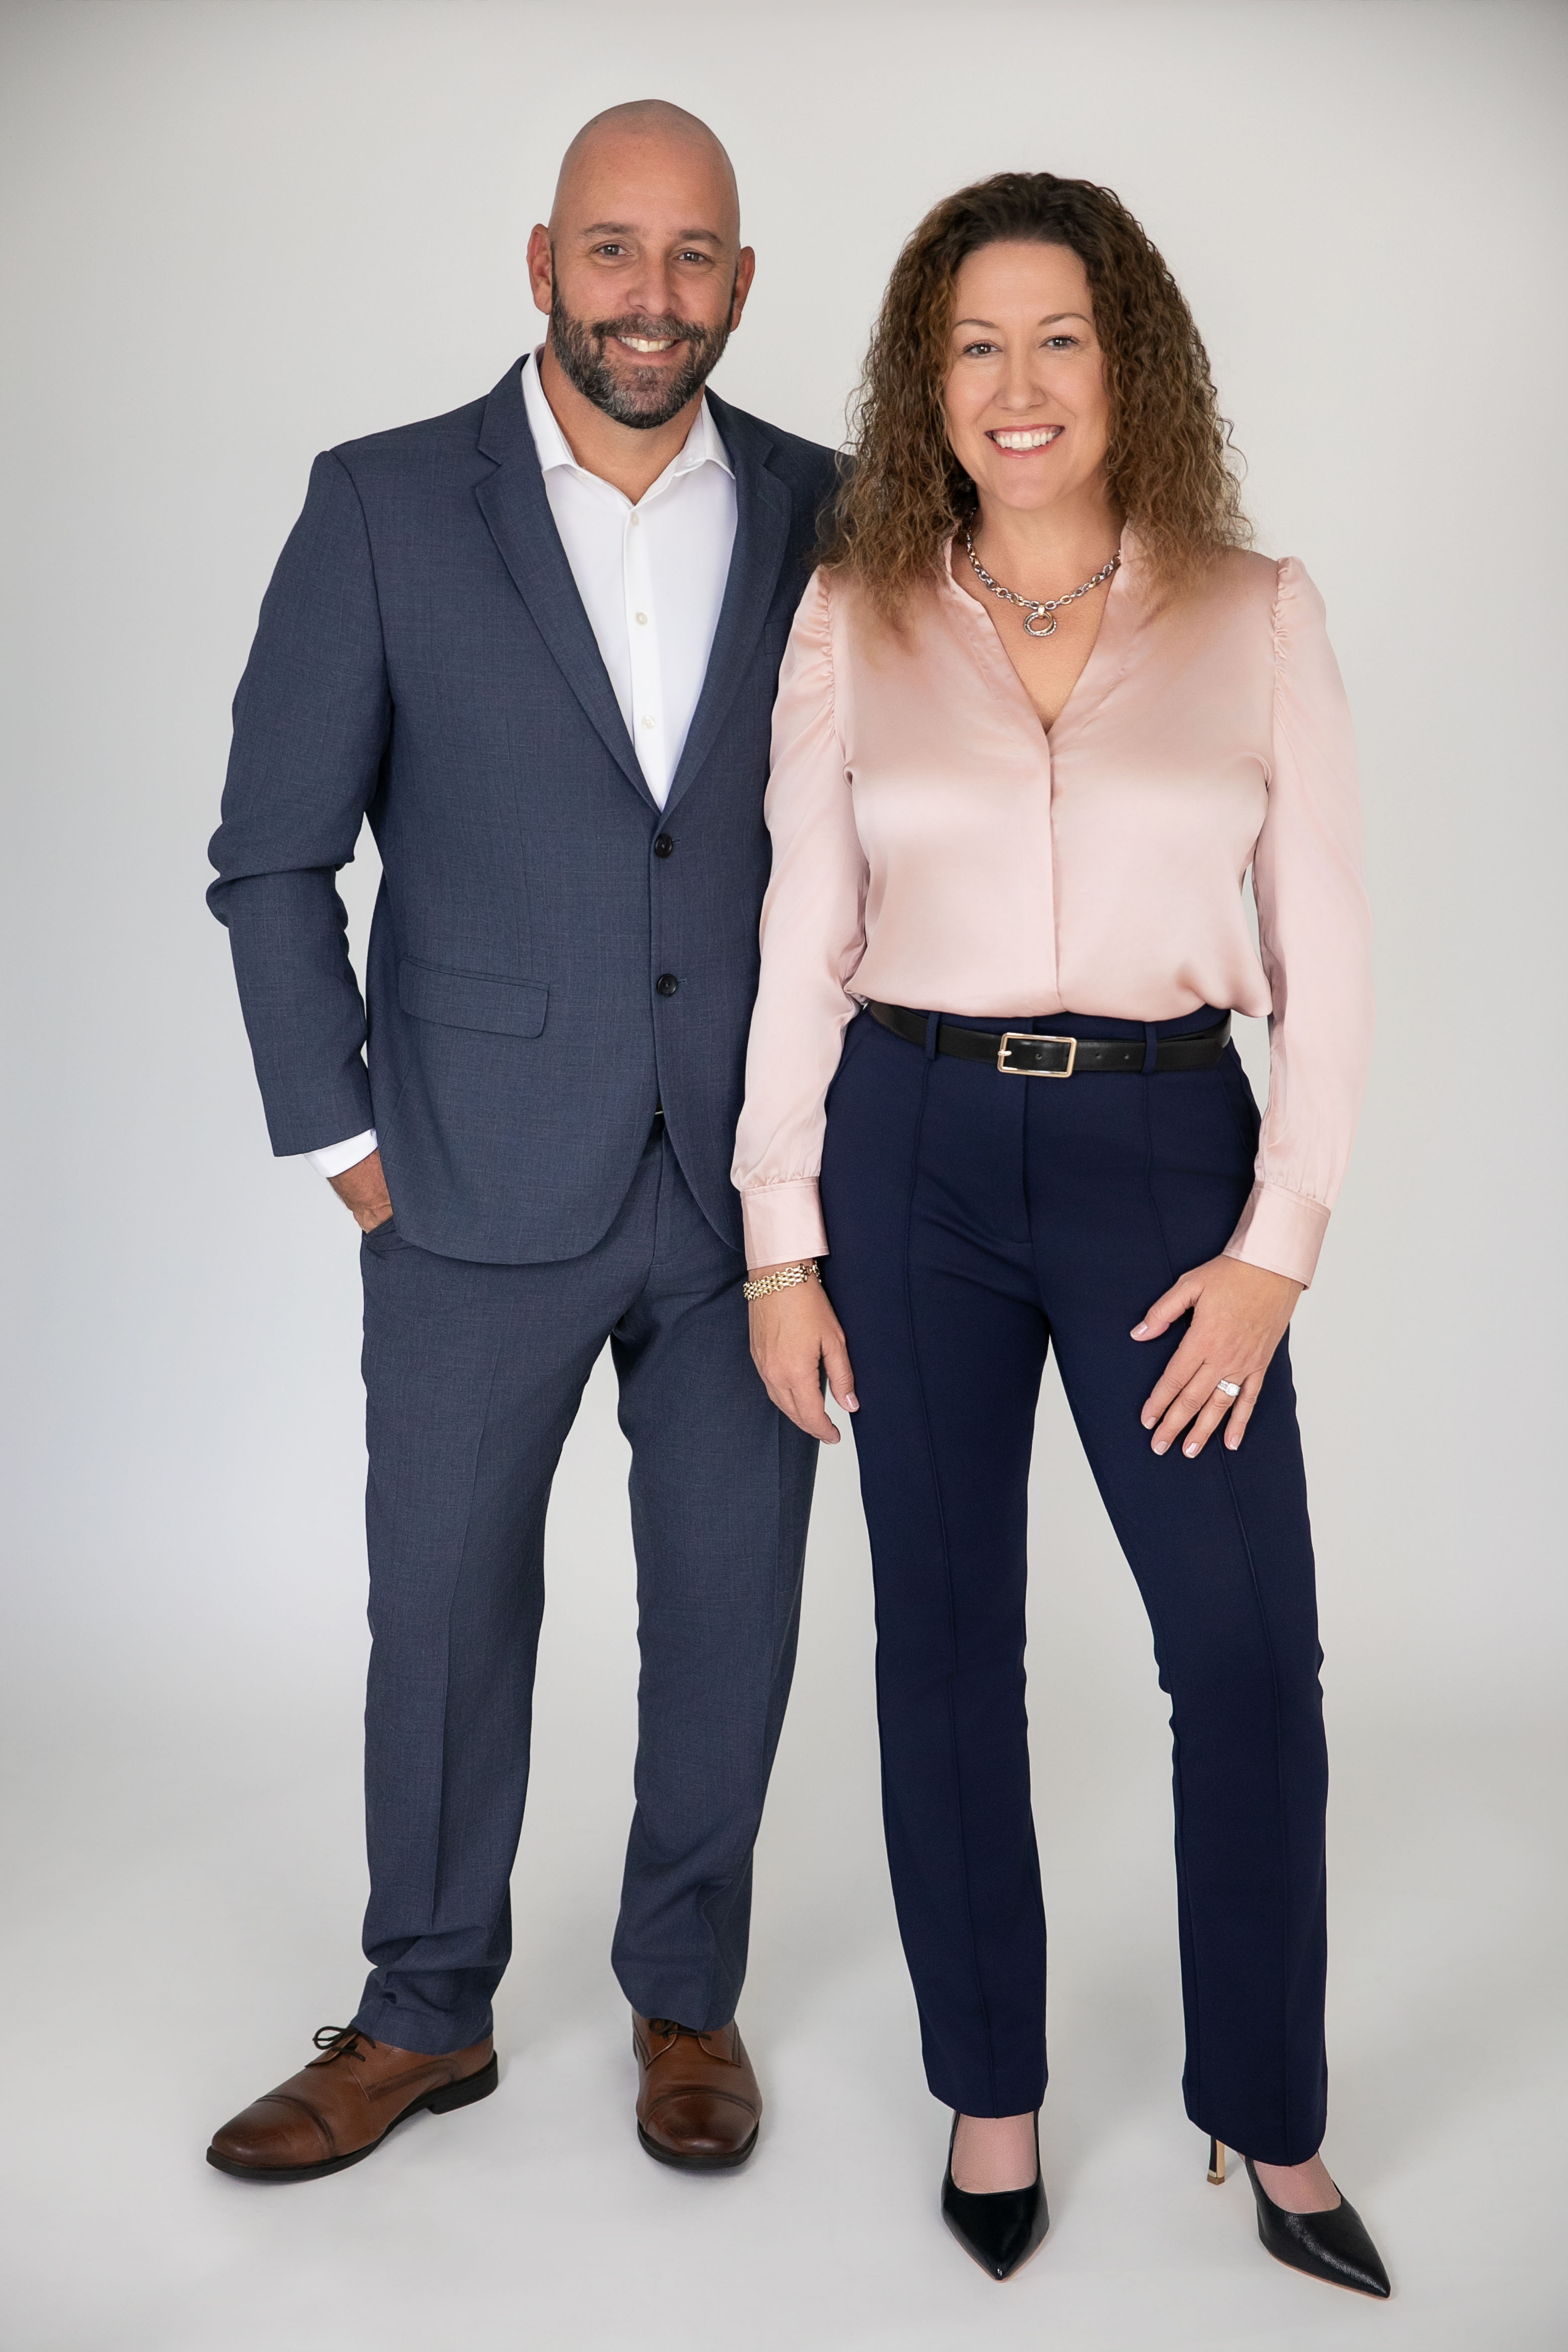
We are Michelle and Jon Dubner, husband and wife, and Dubner Real Estate Group is ours. Our team is here to serve you: to understand what you are hoping for, walk you through it step by step, and make sure you get there. Michelle answers her own phone and is quickest by text, so ask us anything, at any point, however small it feels.
Michelle Dubner DRE #01496647 Jon Dubner DRE #02118617 Equity Union